We're here to help you find the perfect insurance plan. Our team will get in touch.
We respect your privacy. Your details are safe with us.
Our team will contact you shortly to provide personalized assistance with your insurance plan.
You can also reach out to us on 1800 266 1112
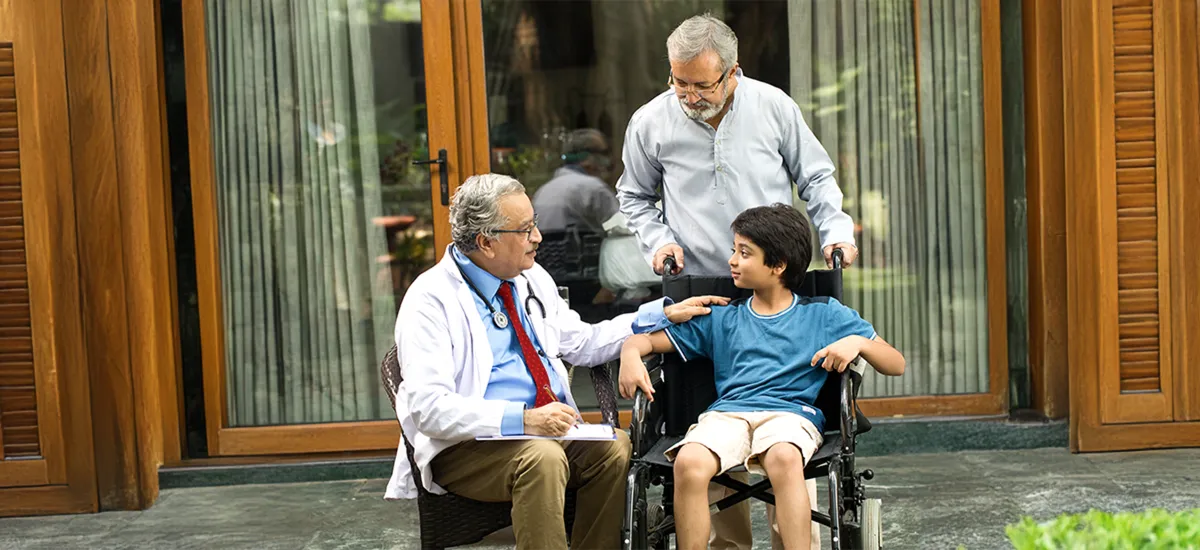
Treatments are important for people to get them out of a certain medical situation like a disease or an accident. While you mostly think of a hospital whenever you hear the word treatment, sometimes it can be brought up in a house. Yes, it is called domiciliary hospitalisation, which doctors recommend in several scenarios. But does a health insurance policy cover it? Can you make a claim for it? Let's find out the answer.
To begin with, let's understand the meaning of domiciliary hospitalisation. It refers to treating a patient at the ease of their home. It means if a patient is being treated at home for their disease; it is called domiciliary treatment. There are many reasons that a doctor may recommend this type of treatment, one of which is the patient's inability to be admitted to the hospital. Now, since the patient is not being admitted to the hospital, their insurer may deny the claim for the treatment expense. Here, comes the role of domiciliary claim.
The domiciliary claim is the component of health insurance which lets you claim the treatment cost in case of domiciliary hospitalisation. So, even if the treatment is brought up at home, the insurance company will cover the cost. However, there are certain terms and conditions for domiciliary claims which ensure that the patient or his/her family members do not opt for the treatment voluntarily.
Let's have a look at three of such conditions where the insurance company will cover domiciliary treatment if they offer the component in their policy:
1. The first condition is very straightforward when the patient can't be moved to the hospital due to the present health conditions. It mostly happens when the patient is old or has a disease that makes moving the patient to the hospital impossible.
2. Sometimes, the hospital cannot treat a patient due to the unavailability of a bed or other equipment. In this case, the treatment is done remotely by any other suitable hospital.
3. Lastly, if it is known that the patient's treatment will take long, moving them to their home becomes a more suitable option. In this case, the domiciliary claim can be made. For example, if a patient is in a coma, then moving them to their home is commonly recommended by the family and the hospital.
However, you should know that a domiciliary claim is not a compulsory component of a health insurance policy. This means you must ensure that your policy covers domiciliary treatment at the time of purchase.
We recommend you opt for FG Health Elite, a health insurance policy for Generali Central's premium customers. It is a family health insurance plan that covers up to 15 family members. It also includes the claim for domiciliary hospitalisation, along with other benefits.
The process of domiciliary hospitalisation mostly replicates the below steps:
1. As the first step, the doctor's consultation takes place. If the doctor recommends that domiciliary treatment should be done for the patient based on their evaluation, then the patient or their family members can move ahead with the procedure.
2. Once the doctor states that it is required, they have to prepare a treatment plan where they brief the treatment requirements, like any medical equipment or a dedicated nurse for everyday medical processes and many more.
3. After that, the patient's family member should share the estimation and treatment plan with the insurance company. If there is any other need, the company will mention it, and the patient's well-wisher has to provide the company with the requirements.
4. If the disease and the treatment for the disease are found to be covered under the policy, the company will give them the treatment green flag. However, if anything is not covered in the policy, like the disease, the company may not pass the claim for the domiciliary hospitalisation.
Here, you must understand that you should have a domiciliary claim as a part of the policy or an add-on. Moreover, you should also know about the sublimity of the claim. For example, if a company offers a 100% claim for domiciliary treatment, you can claim the full amount of the insured sum. But if there's a sub-limit assigned to the domiciliary claim, like 20 or 30%, the max coverage will be restricted to 20 or 30% of the insured sum.
To sum up, this is what domiciliary treatment and claim are. In addition to the above information, you should check a policy's inclusions and exclusions of domiciliary components. For example, some diseases are covered under domiciliary treatment, and some are not. Similarly, you must check the sub-limit of the treatment at home before buying the policy.
You can find the best health insurance plans in Generali Central's DIY Health Insurance, FG Health Absolute, and FG Health Elite.
High or Low Deductible in Medical Insurance
Choosing between a high or low deductible in medical insurance depends on your medical condition and needs. Understand the fundamentals, so you can make an informed decision while purchasing medical insurance. ...
Read MoreDifference Between Riders and Add-on Covers in Health Insurance
When exploring health insurance, you may have come across riders and add-ons. While these sound similar, they are quite different in terms of the benefits that they...
Read MoreWhy Consumables Coverage Matters in Health Insurance
Health insurance provides financial security and peace of mind- until the real hospital bill arrives. Along with medicines, room rent, and surgery expenses, there is always an...
Read MoreCan I Get Health Insurance for a New Born Baby
Sakshi and Shantanu Pandey, both IT professionals from Bangalore, were overjoyed to welcome their newborn. Due to some complications, however, the little one needed to be admitted...
Read MoreTop 5 Benefits of Family Health Insurance | Generali Central
As a responsible provider for your loved ones, ensuring their well-being is likely your top priority. One crucial aspect of this is having a reliable health insurance...
Read MoreGST on Health Insurance: Key Changes Every Policyholder Must Know | Generali Central
The recent exemption of Goods and Services Tax (GST) on health insurance premiums marks a significant shift for policyholders in India. Earlier, premiums carried an additional 18%...
Read MoreSenior Citizen Health Insurance Inclusions & Exclusions | Generali Central
As we age, our healthcare needs evolve, often requiring more frequent medical attention and specialised treatments. For India's growing elderly population, having the right health insurance coverage...
Read MoreHow to Get Free Health Check-Up With Your Health Insurance | Generali Central
When was the last time you went for a preventive health check-up? If you cannot recall, you are not alone. Many of us neglect our health until...
Read MoreWhat is Automatic Recharge in Health Insurance: Benefits, How it Works | Generali Central
Ever wondered what would happen if your health insurance coverage runs out mid-year? Medical emergencies don’t follow a schedule and sometimes, even a high sum insured isn’t...
Read MoreIs Multi-Year Health Insurance a Smart Choice? Pros, Cons & Tips Explained | Generali Central
When it comes to securing your health and finances, choosing the right health insurance is crucial. While most people opt for annual renewals, multi-year health insurance plans...
Read MoreWhat Is Senior Citizen Health Insurance & Why Is It Important | Generali Central
As we step into our golden years, safeguarding our health becomes more vital than ever. With advancing age comes a greater likelihood of chronic conditions, hospital visits,...
Read MoreChemotherapy duration: How long treatment typically lasts | Generali Central
When faced with a cancer diagnosis, one of the most pressing questions for patients and their loved ones is: How long will chemotherapy last? The duration of...
Read MoreHow to Choose the Best Health Insurance Plan for Women | Generali Central
As a woman, your healthcare needs are distinct and evolve through different life stages. With rising medical costs and women's unique healthcare needs, choosing the best health...
Read MorePrivate vs Government Health Insurance Plans | Generali Central
As healthcare costs continue to rise in India, having reliable health insurance coverage is more important than ever. However, with both private medical insurance and government health...
Read MoreHow to Download Ayushman Card Online
Are you struggling to figure out how to download your Ayushman card for availing free health insurance coverage? Many eligible beneficiaries face challenges in obtaining their Ayushman...
Read MorePradhan Mantri Surakshit Matritva Abhiyan
The pregnancy journey is not easy, and thus, women need extra care with regular health checkups and antenatal care. This process can be costly for many, due...
Read MoreWhy It's Never Too Late to Get Health Insurance | Generali Central
Picture this: You're in your 40s, 50s, or even 60s and have been fortunate enough to enjoy good health without any major medical issues. You may think...
Read More: Exploring Health Benefits & Risks of Intermittent Fasting | Generali Central
Explore intermittent fasting for weight loss & better health. Learn its benefits, risks, and types, and see how health insurance supports your wellness journey....
Read MoreTop Cancer Hospitals In Mumbai
Introduction From supporting the maternal duties to establishing the sacred emotional bond with the child, maternity leave in workplaces is necessary for every soon-to-be mother. The Maternity...
Read More